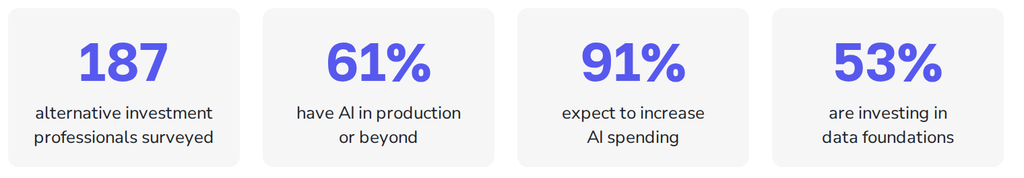
Altvia partnered with UserEvidence to survey 187 alternative investment professionals in September 2026 on market pressure, LP expectations, technology, and AI. The full report publishes in November, 2026. Here is an early look at some of the findings.
AI adoption is real, but uneven
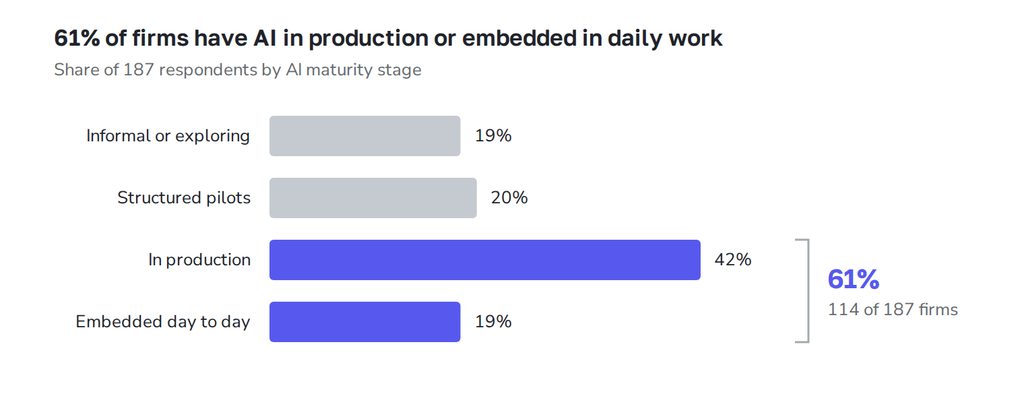
Firms are spread across the maturity curve, and most are past the pilot stage.
The other 39% are still at the pilot stage or earlier.
The barriers aren’t about the models
When we asked what stands in the way of adopting or expanding AI, the top five answers were:
Security or confidentiality concerns: 49%
Integration with existing systems: 48%
Trust in AI outputs and accuracy: 47%
Lack of in-house skills or expertise: 40%
Data quality or readiness: 37%
None of these is about how capable the models are, they’re about safety, connection, trust, and who can use the tools. Only 16% cited unclear return on investment.
The barrier changes as firms mature
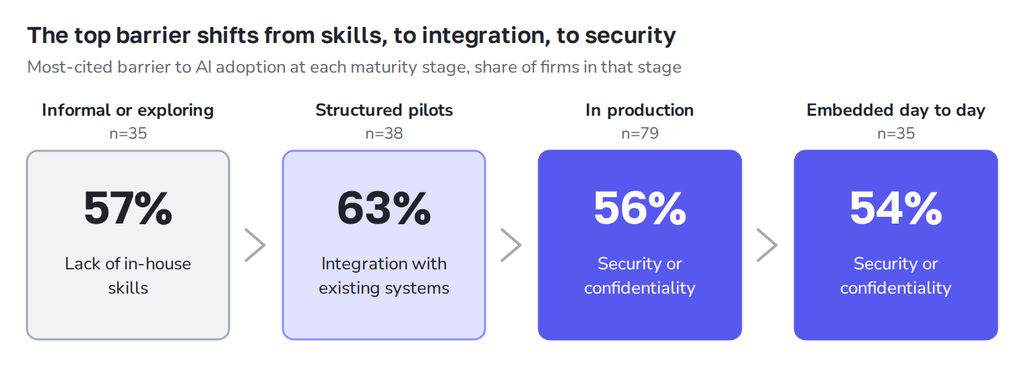
The biggest obstacle is not the same at every stage. Early on, the problem is skills. At the pilot stage, it is connecting AI to existing systems. Once AI is in production, security and confidentiality take over.
Security concern jumps from 23% of firms still exploring to 55% of firms running pilots, and stays above 50% from there.
Skills concerns fade as firms gain experience, falling from 57% of early-stage firms to 32% of those in production. The same three themes appear throughout: who can use the tools, whether the guardrails hold, and whether the data is connected and current. Ryan Keough explores why in 3 Things to Learn from the Automobile When Deploying AI.
Ambition is running ahead of the foundation
91%expect to spend more on AI.53%are investing in the data it depends on.
The firms that are investing report more progress:
Investing in data infrastructure
Not investing
AI in production or embedded
69%
52%
Technology helps them keep pace
82%
66%
“Without quality data, AI can’t do its job,” says Lisa Lewis, Industry Product Manager at Altvia. “Data infrastructure is the next big Achilles’ heel, but unlike launching a pilot or establishing a policy, it’s often a multi-year commitment that nobody gets credit for.”
LP expectations are rising across the board
Respondents reported higher LP expectations over the past 12 months in every area we measured:
LP expectation
Share reporting an increase
Transparency into fund performance
87%
Speed of response to requests
86%
Frequency of reporting and updates
85%
Self-service access to data
84%
Detail and granularity in reporting
82%
What’s next
The full report goes deeper on how these patterns vary by firm size and role, and on what firms are doing about them. Subscribe to get the report.
How Investor Engagement Manager Enables Firmwide Investor Relationships
Summary: Most AI in investor relations delivers value only to the people with the expertise to operate it. Turning that into a strategic advantage the whole firm holds, and one that accelerates, takes three things in place at once. The automobile needed the same three, and took thirty years to assemble them.
By Ryan Keough
For AI to actually move an organizational objective such as investor relations, fundraising, or the strength of every LP relationship a firm holds, three elements have to be in place at the same time.
There is a version of AI success that firms are quietly settling for, and the awkward thing about it is that it works. It produces genuinely useful output, but only for the people who know the data, know how to ask, and can tell a good answer from a plausible one.
That is a real skill. It is also unevenly distributed, and today’s AI is almost entirely dependent on it. The value a firm gets is capped by how many people it has who hold that expertise, and the colleague at the next desk gets something worse without being able to say why.
The three elements
That is a set of capable individuals, not a capable firm. It does not compound, because the value lives in the operators rather than in the organization. And it is not fixed by training, because the dependency is structural: a system that only works in expert hands will only ever reach as far as your experts do.
One. It has to be accessible to the entire team. Usable by everyone who touches the relationship, not dependent on an expert user who knows how to work it.
Two. The guardrails have to be in place. Safe, reliable and governed, which is what allows a team to move fast rather than what slows it down.
Three. It has to have the essential inputs. Clean, connected, current data, arriving continuously, without anyone hand-crafting it.
Any two without the third leaves you with a pilot. All three together is a different thing entirely.
The automobile is the proof
The car is the clearest example of all three arriving, and of how little the machine alone was worth until they did.
Accessible. Early automobiles were for mechanics and enthusiasts: difficult to start, harder to maintain, and priced for the wealthy. The Model T mattered because an ordinary person could afford it and operate it1. Mass value required mass accessibility, not a better engine.
Guarded. Then the roads. Early roads had no lane markings, no stop signs, no signals, no right-of-way conventions and no requirement that the driver knew how to drive. The control layer was invented piece by piece over two decades. Center lines appeared in several states between 1911 and 1917, the first stop signs and signals around 1914 and 1915, and national uniformity only with the first Manual on Uniform Traffic Control Devices in 1935.2 Until then, driving at volume was dangerous rather than useful.
Fueled. And the fuel. Crude oil does not run an engine; gasoline came out of a refining process, as a byproduct of making lamp kerosene, and was so plentiful that refiners burned it off.3 It was never scarce. It simply was not where the driver was. Before filling stations you bought it in cans from a pharmacy or a blacksmith, and planned long trips by telephoning ahead.4 Quality varied with whatever crude it came from, and the property that actually mattered, knock resistance, had no agreed measure until the octane scale arrived in 1930.5
A car nobody could drive, on roads nobody could survive, running on fuel nobody could find, is a hobby. All three together built an industry.
And what the three delivered together was not a better car. It was access. Ordinary people could travel routinely and arrive safely, which changed where they could live, where they could work, and how far a business could reach. Freight moved by road. Rural isolation eased. A machine that had been an enthusiast’s curiosity became infrastructure an entire society ran on, and the people who had it could do things the people who did not simply could not do.
The elements were the enabler. The advancement was the point.
The same three, in our clients’ own numbers
We asked 187 private markets professionals in September what is blocking them.6 The answers map onto those three elements almost exactly.
THE ELEMENT
IN THE CAR ERA
IN AN AI SOLUTION
BARRIER IN OUR SURVEY
Accessible to everyone
A car an ordinaryperson could afford,start and drive, not amachine for mechanicsand enthusiasts.
Value available to the whole team without an expert operator in the middle.
In-house skills: 40%
Guardrails in place
Signs, painted lines, barriers, and rules of the road, so speed was survivable.
Permissions, traceability, auditability, and human approval, so the firm can move fast.
Security 49%, trust 47%
The essential inputs
Refined fuel, available where you needed it, at consistent quality.
Clean, connected, continuously replenished data, delivered without manual effort.
Integration 48%, data readiness 37%
Security 49%, integration 48%, trust in outputs 47%, in-house skills 40%, data readiness 37%. Not one of the top five is a model problem. Every one is one of the three elements being absent.
It shows where firms are stuck: 19% informal or exploring, 20% running structured pilots, 42% in production, and only 19% with AI embedded in day-to-day work. Four in ten have not reached production at all. The middle of that curve is crowded with firms that have proven something works for somebody and cannot get it to work for everybody.
Investor Engagement Manager was built around these three elements rather than around a model. Each one is a deliberate design decision, and the combination is what turns AI from a capability into an advantage a firm actually holds.
How IEM puts the three together
ONE · ACCESSIBLE TO THE ENTIRE TEAM
IEM changes how the work gets done, and it does it for everyone.
The expertise the current generation depends on is not something IEM asks the user to supply. The intelligence is surfaced by the system and embedded in it, rather than drawn out of it by someone who knows how. There is no prompt to compose, no need to know where the data lives, no judgment call about whether an answer can be trusted, and nothing a person has to understand about how AI works in order to benefit from it. IEM surfaces what changed across every LP relationship, explains what is driving it, and puts a recommended next step in front of the person who covers it.
That design choice does something a better model cannot. Because the experience is the same for everyone, the quality of preparation is the same for everyone. The associate, the IR lead and the partner all start from the same place. Value stops being a function of who is good at the tool, which means it scales with the size of the team rather than with the number of experts on it.
TWO · GUARDRAILS THAT LET THE TEAM MOVE FAST
A system that moves first has to meet a higher standard, and IEM is built around four commitments.
Secure. IEM reads inside the firm’s existing permissions rather than building a second access model beside them. What it surfaces to any individual stays bounded by what that person could already see.
Traceable. Every alert, assessment and draft ties back to the record it came from. Nobody is asked to accept a number on faith.
Auditable. What was surfaced, what was recommended, who saw it, who approved it and what was done, all reconstructable afterward.
Human-led. Nothing consequential reaches an investor or changes a record until a person approves it.
The instinct is to read that list as friction. The roads say otherwise. Lane markings and signals did not restrain traffic; they are the reason traffic could move at volume and at speed without constant collision. Guardrails are what make speed possible, and they are the difference between a firm piloting AI in one corner and a firm running it everywhere.
THREE · THE INPUTS THAT MAKE IT WORK
No firm in private capital is short of data. It accumulates as a byproduct of the work, whether email, documents, fund reporting or notes, and like crude in the ground, none of it runs anything in the state it arrives in. It has to be refined: resolved, connected, deduplicated, put in context. Most of it never is. It sits where it landed.
Firms tend to judge their data by whether the CRM looks populated, which is the equivalent of grading fuel by specific gravity: easy to measure, and not the property that determines whether the engine runs.
Altvia’s underlying data management and data model is what turns that raw material into an enabler rather than a constraint, and the governing principle is that refining cannot depend on the user. That is the lesson of every CRM adoption program ever run: if the value requires people to faithfully enter data first, the value does not arrive. So we handle it three ways.
1. We refine the data you already have. Existing records cleaned, connected and put right, so the firm’s history is usable from day one rather than after a migration project. Nobody starts with an empty tank.
2. We embed data consumption, so nobody hand-crafts the fuel. Integrations and imports keep other systems feeding in automatically. The picture stays current without anyone copying between tools or maintaining a second record by hand.
3. We consume unstructured email automatically. Email is the richest and least governed record of an LP relationship. It is captured, cleaned, organized and recorded into the CRM without user involvement, and made available to IEM without anyone filing anything.
The common thread is that none of the three require a person to be diligent for the system to work. That matters more than it sounds. A system reading only what people remembered to type is reading a fraction of the relationship, and the fraction is biased toward whoever is most dutiful about paperwork, which is rarely the person closest to the investor.
This is how siloed data becomes organizational intelligence: refined, pumped into the tank, and available to everyone entitled to see it.
No one person holds the whole LP relationship. With the inputs handled this way, the firm holds it, even when the individual who built it has moved on.
From changing the work to changing what the firm can do
Each element on its own is worth something and capped. Accessibility without guardrails is a fast car on an unmarked road. Guardrails without accessible value is governance over a pilot nobody uses. And either of those without clean, continuous inputs is an engine with nothing in the tank.
Together they change the work itself. Coverage stops depending on how many relationships a team has the bandwidth to work. Preparation arrives assembled rather than assembled by someone. The quiet relationship that was drifting gets surfaced while there is still time, and the re-up picture arrives months before a launch rather than during the raise.
But the change to the work is the smaller half of it.
Mass access to the automobile did not simply make individual journeys easier. It changed what was possible for the people and the businesses that had it, and it did so at the level of the whole enterprise rather than the single trip. The same thing happens here. A firm where every person works from the same quality of preparation, where coverage no longer tracks bandwidth, and where institutional memory survives the departure of the person who built the relationship, is not performing the old job more efficiently. It is operating at a level its competitors cannot reach by working harder, because working harder is precisely what the constraint always was.
That is a strategic advantage, not an operational improvement. And unlike an operational improvement, it accelerates.
Every interaction connected makes the next connection sharper. Every proactive pass improves the one after it. The firm’s accumulated history becomes an asset a competitor starting today cannot simply buy, because the only way to acquire it is to have been compounding it already. The gap does not stay the same size; it widens in favor of whoever assembled the three elements first.
That is the difference between deploying AI and gaining ground because of it.
Launching with all three
Investor Engagement Manager is available today, with the data refined and continuously replenished, the guardrails built in rather than promised, and the value accessible to every person on the team without an expert in the middle.
The automobile needed thirty years to assemble those three elements, and the assembling is what cost the time. The findings are published now. There is no reason for a firm in private capital to repeat the experiment.
In the first post of this series, we argued that every AI strategy has to answer four questions: what advantages does AI create, what are the risks, what is the integration plan, and in what sequence should that plan be executed?
The first two questions, what the advantages are and what the risks are, have answers specific to each firm. This post expands on the advantages and risks for the relationship that matters most to a GP: the one with the LP.
What AI can do for the GP/LP relationship
The obvious answers to the question of AI advantages are already familiar:
Draft an LP email
Read a year of interactions and estimate how healthy a relationship is.
Summarize a call and flag an overdue follow-up
Fill in the fields nobody filled in
These are useful, and every serious platform will offer some version of them. They are also generic AI use cases with a private markets vocabulary applied. A firm that stops there has bought a faster version of work it already does.
The strategic advantage is the firm’s capacity to hold LP relationships at depth. Today that capacity is set by headcount and memory. A team of three can know forty relationships well, and the rest get the newsletter. Institutional knowledge like who cares about what, what was promised in the last meeting, and which contact is the actual decision-maker, lives with the people who happen to cover the account. And then it’s lost when they leave the firm.
The advantage AI can deliver, if it’s built for this purpose, is that this deep relationship context, the kind of context that isn’t typically found in an account record, is housed and understood across the firm, all the time. Partner-level judgment can be applied on any of them at the moment it matters.
Why LP relationship depth matters more between fundraises
Capital is concentrating with managers LPs already know. Bain’s 2026 Global Private Equity Report finds that 53% of LPs are constrained from making new commitments because capital they already pledged has not been called, up 15 points in a year. The number of buyout funds reaching a close fell 23%. In this market, the relationship a firm carries into the fundraise decides most of the outcome before the first meeting.
The benefits of a deeper relationship compound in ways that show up across the private markets business:
An LP who knows the firm re-ups, and at a larger allocation
Diligence moves faster, because the DDQ confirms what is already established rather than examining it
First closes get anchored, which pulls the rest of the roster forward
Co-investment and separate account conversations get a serious hearing
A continuation vehicle has real support behind it when the firm needs one
A difficult quarter comes with room, and with people who speak well of the firm to the consultants and peers who shape the next fundraise
Every one of those outcomes is earned in the quarters when no fund is in market and where relationship capital is built through interactions like reporting delivered on time, questions answered fully, and follow-ups kept.
How LP relationships are lost between fundraises
It’s in these same quarters where relationships are lost, and they’re lost quietly. Most of the LPs a firm loses are still on the list when the fundraise opens. They took the calls, they received every report, there’s nothing in the file that indicates anything changed. Then the commitment comes back smaller, or as a polite note that this cycle is a pass.
This kicks off an internal process where the team tries to dissect the moment it went wrong. Was it a quarterly report that landed late during the LP’s reallocation? A champion who moved to a different mandate and a successor who never got the call? A follow-up from the annual meeting that stayed in a drafts folder?
Commitments recede before anyone declines. A firm can lose an LP before the fundraise begins and still has to earn every commitment when it does.
Why CRM and a disciplined IR team stopped being enough
Ten years ago, a good CRM and a disciplined IR team was a system that worked. Both still matter, what’s changed is the shape of the business around them. Firms added continuation vehicles, co-investment sleeves, separately managed accounts, and new strategies to stay relevant to the same LPs. Each addition brought its own reporting calendar, its own LP segment, and one more place for the story to diverge.
In Altvia’s interviews with IR teams this year, the recurring theme was learning about an important LP change later than they wanted and not having a system that would have surfaced it. They all knew the data was somewhere within the firm, but nobody had time to find it.
The risk question: the LP relationship answer
The generic risks are leakage and fabrication, and every vendor addresses them. The specific risks within an LP relationship define what the tools have to do.
Under the SEC Marketing Rule, a communication that offers advisory services to prospective or current private fund investors can be considered an advertisement and carries the obligations that follow. The line between an ordinary LP update and an advertisement is not always obvious. A system that drafts for IR therefore has to stop before the send and wait for a person to take the next step.
Additionally, every figure carries the firm’s reputation, so a number with no visible source is a number nobody can defend in the meeting. Partners want to know what the model can access and where the data goes. In one beta conversation this year a partner returned to that question three separate times.
And the IR and fundraising function is starting from behind: in Altvia’s forthcoming 2026 Private Markets Survey, investor relations and fundraising respondents report the lowest AI maturity of any function, a mean of 3.1 on a 0 to 5 scale, and the lowest confidence in AI accuracy, 29% against 47% of all respondents. A strategy that hands them a general-purpose assistant and a training session has misjudged both the advantage and the risk.
A Standard Emerges
Put the advantage and the risks together and a standard emerges:
AI for the LP relationship holds the full relationship in one place, with the deal and fund context that shapes it, so the firm’s knowledge of an LP no longer depends on who covers the account.
It captures that relationship with less manual effort each quarter, because a system that depends on someone remembering to update it inherits the failure it was meant to fix.
It brings the right slice of the relationship to the right person at the right moment, with the source shown.
And it proposes while a person approves.
That standard is what Altvia means by a GP Engagement Platform. Stay tuned! The next post in this series delves into the third question: what’s the plan, in practice?
Sources
Bain & Company, Global Private Equity Report 2026, Fund-raising section (published February 22, 2026). https://www.bain.com/insights/outlook-gaining-traction-global-private-equity-report-2026/
U.S. Securities and Exchange Commission, Investment Adviser Marketing, Release No. IA-5653 (the Marketing Rule, Rule 206(4)-1 under the Investment Advisers Act of 1940). https://www.sec.gov/rules-regulations/2020/12/investment-adviser-marketing
Last month I wrote about what I heard at PEI’s IR Network meeting: I saw a room full of IR professionals working out, in real time, how to use AI without letting it do the thinking for them. A few weeks later I was back in the room, this time at another PEI IR Network meeting. The same core questions were on the agenda, but this time was different.
Last month’s conversation was mostly internal: how do we use AI? How do we not get it wrong? What will our LPs think if they find out? Last week, the conversation had shifted. LPs aren’t just forming opinions about AI use anymore. They’re asking directly how GPs are using it, and that means GPs have to think differently about their AI strategy.
Here’s what stood out.
Personalized LP communications are the clearest AI use case, and also the trickiest one
The most concrete idea I heard came from a conversation about turning deal memos into short, personalized notes for LPs, rather than generic updates. It’s a good use case: the raw material already exists, and AI is well-suited to reshaping it into something that reads like it was written for one person rather than a distribution list.
But the group was candid about where the line sits. There’s a real distinction between the low-hanging fruit (a quick capsule summary) and what would actually be meaningfully impactful. This almost always requires pulling data from a lot of different sources and takes real work to get right: IC summaries, LP meeting notes, and reporting all live behind different systems, often in different formats. Nobody in the room felt like they’d fully solved this. As one person put it, the real bottleneck is data quality: garbage in, garbage out. The hard part isn’t the AI, it’s getting information into a usable format in the first place. It’s a theme that came up again and again last week: technology is rarely the constraint. The underlying data infrastructure is.
Confidentiality is a harder line than it was six months ago
This came up more specifically at last week’s meeting. Sub docs and other sensitive materials can’t just get pushed into a general-purpose LLM. That’s not a compliance nicety; it’s a real operating constraint that shapes which tools a firm can actually use and how. It’s consistent with what Deloitte found in its 2025 GenAI in M&A Survey of 1,000 corporate and PE dealmakers: data security was the single most-cited barrier to GenAI adoption, ahead of every other concern. For private capital firms, where sub docs, LPA terms, and side letters are about as sensitive as documents get, that distinction isn’t theoretical.
At the same time, LPs want more from their GPs, not less. More data and more transparency. So GPs are stuck trying to do both at once: securely share more, but never make it feel like a bot did it. One comment from the room stuck with me: “Nobody wants their IR comms to read like ‘a bot.'” That’s the same reputational risk I wrote about in my last post, except now LPs are actually asking the question, not just wondering about it.
LPs are starting to ask GPs directly how AI is used in the firm
It’s no longer hypothetical that an LP might wonder about a GP’s AI adoption. LPs are now asking. The data backs this up: Private Equity International’s LP Perspectives 2026 Study found that nearly half of LPs surveyed are closely monitoring how their GPs adopt AI in investment and operational processes, and almost as many report mixed feelings about it, largely driven by risk concerns. The ILPA DDQ framework, which the majority of institutional LPs now use as a baseline for manager evaluation, continues to expand with each cycle, and it would be reasonable to expect AI governance to become a standard section, rather than an ad hoc follow-up question.
If your firm doesn’t yet have a clean, honest answer to “How do you use AI, and what guardrails are in place?” it’s time to build one. Not because someone will send it back with a red pen if you get it wrong, but because you should probably be able to answer that question clearly, regardless of who’s asking.
The fee conversation nobody wants to have, but needs to
If firms are getting more efficient because of AI, will LPs start asking why fees haven’t come down? It was framed as hypothetical, but it’s not disconnected from what’s actually happening in the market. Bain’s 2026 GP Outlook already points to real downward pressure on headline management fees, particularly at scale. A recent bfinance poll found that a large share of LPs report fee reductions for like-for-like private market strategies, with softer fundraising and disappointing distributions shifting real pricing power toward investors.
AI efficiency gains and fee pressure are two separate trends right now. But it’s not hard to see an LP putting them next to each other, and GPs should probably have a point of view before that question shows up in a meeting. The best response is to show where the efficiency actually goes: faster answers, better reporting, more time for the relationship itself. That’s a different story than “we cut costs and kept the fee the same.”
MCP servers came up, unprompted
Someone in the room made an offhand comment: if you already know what an MCP server is, you’re ahead of the curve. It’s a small signal, but it’s consistent with where the infrastructure conversation is heading. Most firms are still thinking about AI at the level of individual tools and prompts. Fewer are thinking about the underlying protocols that let those tools connect to a firm’s systems and data securely. That gap between “using an AI tool” and “having AI infrastructure” is expected to keep widening.
Where this leaves us
The first meeting focused on where and how IR teams should utilize AI. The second made it clear the conversation has moved past that. LPs are asking direct questions, fee dynamics are shifting underneath the AI conversation whether anyone planned for that or not, and the confidentiality line between what can and can’t touch a general-purpose LLM is getting firmer, not softer.
The through-line from both meetings hasn’t changed, though: the firms that feel most at ease are the ones with real infrastructure and clear answers, not the ones with the most impressive prompt. If anything, last week’s session raised the stakes on that point. An LP asking how you use AI in a DDQ isn’t looking for enthusiasm. They’re looking for governance.
Recently, senior IR leaders gathered at the PEI IR Forum to get specific about what’s changing in fundraising and LP relationships. What came through were genuine discussions around real operational gaps, current LP expectations, and the role AI is starting to play in both. The distance between knowing it and doing something about it is where firms are separating.
Here’s a recap of the most salient points from the event:
Trust is the rarest asset in the room
Professor Paul Argenti opened the Forum with a number that stops the conversation: only roughly 30% of stakeholders trust private markets firms. The response from the room wasn’t panic, but it wasn’t dismissal either. The firms earning trust aren’t doing it through volume, they’re doing it through consistency, clarity, and alignment between what they say internally and what they communicate to LPs. The GP who tells a different story in the quarterly letter than they did in the last fund close creates an LP who remembers both versions. That gap leads to the next point….
LPs are already using AI on your communications
This point came up in a panel on resiliency in a shifting macro landscape, hosted by Ray Grant, VP of Strategic Initiatives and Partnerships at Altvia. The panel’s central argument was that consistent, proactive communication across multiple channels is the baseline for maintaining LP confidence:
Email updates that don’t wait for the quarterly cycle
LP portal as an always-on resource, not a document dump
Direct outreach timed to material events, not just scheduled intervals
One of the more memorable moments came from a panelist who made the case for embedding your firm narrative into internal culture, not just external communications. The analogy: put broccoli in front of your kids every day until they start eating it. The teams sending consistent messages to LPs are the ones who have made that narrative part of how the firm operates internally, across every function that touches an investor relationship.
LPs are also raising the stakes on consistency in a more direct way. They are running AI tools against the full history of their GP relationships, checking prior communications against current ones, looking for inconsistencies, promises not kept, language that drifted. The implication is direct: if LPs now have a complete, searchable view of the relationship, IR teams need to as well. The information asymmetry that GPs once held has inverted.
On AI: don’t build your own
There was notable consensus in the room against firms attempting to build proprietary, integrated AI solutions. The reasoning may seem counterintuitive: off-the-shelf commercial tools impose standard operating procedures on users while custom builds create perpetual exceptions. As one panelist put it, private markets firms are not technology companies and shouldn’t pretend otherwise. Find a trusted technology partner. Don’t reinvent the infrastructure.
That said, AI is genuinely useful in specific applications:
Drafting LP communications
Accelerating data hygiene
Flagging engagement signals
Where it falls short is in replacing the human judgment that distinguishes a fund update from a form letter. Panelists flagged “AI voice” as a real risk in quarterly reports, where the prose starts to read like no one in particular wrote it. The consensus: AI works best as an enabler of better thinking and faster execution, not a shortcut for strategy or voice.
IR and marketing are converging on compliance
One of the more practical sessions focused on cross-functional alignment. One panelist described an IR team that was unaware of a capital call posted the day before an on-site LP meeting. The LP asked questions the team couldn’t answer. That kind of gap is no longer acceptable. The firms getting ahead of that problem are the ones bringing IR, legal, compliance, and finance together earlier, treating compliance as a partner in messaging rather than a final checkpoint. It’s a structural change, not a process tweak.
The thread running through all of it
IR has to be proactive. As one keynote framed it, you’re fighting for the re-up every single day in every touch between formal raises. That’s not a new idea, but the operational requirements for actually doing it are changing. LPs are more sophisticated, better equipped, and more willing to redirect capital based on the experience of the relationship rather than performance alone. The gap between what LPs can see and what GPs can see is closing, whether GPs are ready for it or not.
None of it works without the foundation
Near the end of the AI panel, the moderator asked for a show of hands: who feels confident they have a single system capturing all LP data across IR, fund administration, and accounting? Zero hands went up.
That moment was the most honest summary of where the industry actually stands. Proactive IR, AI-enabled communications, co-invest tracking, re-up intelligence: all of it depends on LP data that is clean, connected, and current. Fragmented systems don’t just slow teams down. They create the exact gaps that LPs are now finding for themselves.
Altvia is built on that foundation: a platform purpose-built for the full capital raise and LP engagement lifecycle, with data integrity at the core rather than bolted on after the fact. If any of this maps to conversations your own team is having, we’d welcome the next one. Request a demo.
We’re just back from the With Intelligence Women’s Private Equity Summit in Arizona, where more than 1,400 women across private markets spent two days in the kind of frank, practitioner-level conversation that rarely makes it into published reports.
WPES has a way of surfacing what firms are actually grappling with, not just what they’re presenting to LPs. And this year, the operational themes were hard to ignore. The frustrations being voiced in both sessions and hallways track closely with what we hear in conversations with GPs, IR teams, and fund operators across the market. Five of them are worth unpacking.
1. Speed Is the New Competitive Variable in Fundraising
The firms that are closing faster are not necessarily running better strategies. They’re running tighter operations.
Across conversations at WPES and in our broader work with private capital firms, the consistent pressure point is the gap between relationship activity and execution. Meetings happen. Notes get taken. Then the follow-through slows down because moving information from an LP conversation into a structured record, a task, and an investor communication requires manual work at every step.
That friction compounds quickly. In a fundraising environment where LPs are receiving more outreach, evaluating more managers, and consolidating commitments, the speed at which a firm can respond, update, and advance a relationship is a real differentiator.
What firms need is not more effort, it’s automation of the repetitive handoffs: meeting to CRM system, CRM record to follow-up, follow-up to investor communication. The firms building that infrastructure now are shortening their cycles. The ones that haven’t are spending the same time on processes that their competitors are spending on relationships.
2. Most Firms Know What Good LP Communication Looks Like. Fewer Have Built It.
This is the operational challenge that has been acknowledged for years and solved by very few.
GPs know they need to communicate with LPs consistently. They know that transparency and responsiveness are core to re-up decisions. They also know that when multiple people on a team interact with the same LP across different contexts, and none of it is centrally tracked, the quality of that communication degrades fast.
What gets surfaced at events like WPES is not a new problem. It’s the same problem, stated with more urgency. Firms need a complete, accessible view of every LP interaction across the team. They need communication workflows that create structure without creating friction. And they need visibility into where relationships are strong, where they’ve gone quiet, and what needs attention before it becomes a problem.
The firms that have operationalized this are not doing anything heroic. They’re using better systems and more disciplined processes. The gap between them and the firms still managing LP communication in spreadsheets and inboxes is widening.
3. Data Is the Prerequisite. AI Is the Benefit.
AI came up constantly at WPES, and the conversation has matured considerably from where it was a year ago. Nobody is talking about replacing human relationships with automation. The focus is on what AI can do when it’s embedded directly into fundraising and IR workflows: capturing data, surfacing patterns, flagging follow-ups, generating insights from relationship history.
But there was a consistent thread of honesty running through those conversations. AI only works well on good data. Firms that haven’t solved their data capture problem – meeting notes that never make it into a system, interaction history that lives in individual email threads – are not going to get meaningful value from AI tools layered on top of that foundation.
The sequencing matters: data ingestion first, data quality second, AI-powered insights third. Firms that try to skip to the third step are going to be disappointed. Firms that treat data infrastructure as a prerequisite are positioning themselves to extract real value from the AI investments they’re already making.
This is not theoretical. The use cases that are gaining traction right now are narrow and practical: auto-generating account record entries from meeting notes, identifying LPs who are overdue for outreach, combining fund administration data with relationship data to produce more meaningful LP reporting. None of it is complicated. All of it requires clean, connected data to work.
4. AI Adoption Is Still Experimental, and That Window Is Closing
The honest read on AI in private markets right now: most firms are in the experimentation phase. Pilots are running. Use cases are being tested. Measurable impact is still limited.
That is not a criticism. It reflects where the industry genuinely is. But the firms that treat experimentation as a permanent state are going to fall behind the ones that are building toward adoption at scale.
What separates those two paths is change management. Technology does not change behavior on its own. If an AI tool requires a new workflow and nobody is accountable for driving adoption of that workflow, the tool will be used by the three people who were already interested and ignored by everyone else.
The firms making real progress on AI are treating adoption as an operational problem, not a technology problem. They are defining what behavior change looks like, measuring it, and holding teams accountable for it.
5. Raises Are Continuous. Most Operations Aren’t Built That Way.
The session that resonated most at WPES reinforced something that shows up in our own data and client conversations: the strongest fundraising firms are not raising episodically. They are managing LP relationships with the same discipline between closes as they apply during an active raise.
LPs said it plainly. They want proactive engagement, not just inbound responses when a fund is in market. They want to know what is happening in the portfolio, what has changed in the team or strategy, and that their GP is thinking about them specifically, not sending the same update to a distribution list of 200.
The operational implication is significant. Building and maintaining that kind of continuous relationship management requires infrastructure. It requires a system that tracks every interaction, surfaces the right follow-ups, and enables a small IR team to sustain meaningful engagement across a large LP base without losing quality.
That is what purpose-built private capital platforms are designed to do. And it is what general-purpose CRMs adapted for private markets consistently fail to deliver.
The Pattern Across All Five
Look at the five themes above and a single thread runs through all of them: the work is operational. Speeding up the fundraising cycle, maintaining consistent LP communication, building a data foundation that makes AI useful, driving adoption rather than just deployment, sustaining relationship engagement between closes – none of it happens without operational infrastructure behind it.
That shift is creating a new kind of competitive differentiation in private markets. Firms with disciplined IR operations are responding to LPs faster, communicating more consistently, and entering each raise better prepared. The advantage compounds because the infrastructure carries forward across funds.
Altvia is built for exactly this layer of the business. Connecting fundraising workflows, LP communication, analytics, and reporting into a single platform gives IR teams the visibility and workflow structure to operate with that kind of consistency, not just during a raise, but every day leading up to it.
“The best time to raise your next fund is the day after you close your last—so you’re in perpetual fundraising motion.”
Many firms treat fundraising as a mode they enter and exit. Communication intensifies when the fund is officially in-market, meetings multiply, and materials get polished. By the time a firm formally launches its raise, most LPs carry a quiet, but strong, bias toward or away from a re-up.
This creates the core tension in how most IR teams operate: their energy concentrates at exactly the moment the outcome is already largely determined.
What LPs Are Actually Evaluating
Institutional LPs do not evaluate managers quarter by quarter. They build a confidence profile over years, shaped by an accumulation of interactions that individually feel minor but collectively form a durable impression. Every quarterly report that arrives with inconsistent numbers, every LP question that takes four days to answer, every material issue disclosed reactively rather than proactively—these interactions update that profile continuously, regardless of whether a fund is in market.
LPs look beyond numbers; they evaluate how a firm listens, captures context, and coordinates responses. According to CSC’s research across 150 LPs in North America, Europe, and Asia Pacific, 85% had rejected an investment opportunity over operational concerns alone, and 68% now rank operational clarity above historical returns when evaluating a manager.
The implication is important: your IR function is being assessed continuously, and the assessment is as much about what you say than about how reliably your operating model delivers on it.
The Problem With Managing Relationships in Inboxes
During Altvia’s February 2026 fundraising webinar, Matt Curtolo, GP/LP Advisor, MC Advisory, made the operational challenge concrete: “If you think about Dunbar’s number, you can have 150 relationships that your brain can really handle, and above that you start to lose context. Most IR systems should have multiples of that, and you need detailed notes about those folks.”
A mature firm is managing hundreds of LP relationships, each with distinct preferences about communication cadence and what they need to see before committing. Managing that at scale in spreadsheets and email inboxes works until it stops working, and it stops working quietly—through context that degrades, follow-ups that lag, and preferences that get lost between interactions, or worse, loudly when the wrong document is sent to the wrong person.
During the webinar, Jeff Willems, COO, Triton Lake described the operational discipline required to solve this: his team captures granular data on every LP’s investment preferences, tracks where each relationship sits in the engagement cycle, and uses workflows that prompt the team to follow up when the right trigger is reached. Some LPs want frequent engagement and are comfortable being chased. Others have indicated they prefer to receive deal flow and will reach out when something is relevant. Both preferences need to be honored systematically, not just by the person who originally captured them. When that person leaves or shifts roles, that context should not leave with them.
This is precisely what Altvia is built for. Engagement tracking at the document level, combined with workflow automation for 24- and 48-hour response standards, means the firm’s behavior toward LPs is consistent and professional regardless of which individual is handling the interaction.
The Cost of Inconsistency
LPs do not all react the same way to operational friction, and that is part of what makes it so difficult to manage. Some will flag an error immediately and forcefully—a single number that does not reconcile in a quarterly report can generate a call within the hour, with little patience for explanation. Others absorb the friction quietly and say nothing. With that second group, the signal shows up later and indirectly: slower internal approvals, more diligence questions than expected, reference requests that feel excessive, commitments that arrive smaller or later than anticipated. The vocal LP at least tells you where you stand. The quiet one has already started forming a view about your next fund, and you will not find out until you are in market.
Disconnected systems—a CRM that does not talk to fund administration, reporting that lives in a spreadsheet no one can verify is current, LP communications that go out of one team member’s inbox without being logged anywhere—create the conditions for that erosion at scale.
Altvia’s connected intelligence approach addresses this directly. A single source of truth across IR and deal teams means LP responses draw from the same data regardless of who delivers them. Automated reporting eliminates the version-control problem that produces inconsistent numbers. And the LP Portal gives investors a consistent, branded, audit-ready experience of the firm that reinforces professionalism at every touchpoint.
Why the Off-Cycle Period Is the Fundraise
Firms that operationalize LP relationship management see a different dynamic when they return to market. Conversations start warmer because the LP has been consistently served in the interim. Diligence compresses because the operational track record is self-evident. Reference calls reinforce the relationship rather than having to rescue it, because existing LPs can speak to the quality of the off-cycle experience and not just the deal returns.
In a market where average fund close times have stretched to over 20 months and capital is concentrated with fewer, more trusted managers, the off-cycle period is not the gap between fundraises. It is the fundraise. The firms that recognize this—and build the systems to execute on it continuously—are the ones LPs move fastest for when the time comes.
Performance still matters most in fundraising. Strong returns earn attention, secure first meetings, and open allocation discussions. But once a firm is in consideration, momentum is shaped by something more subtle: how easy it is for LPs to underwrite the opportunity.
That is where friction enters the picture.
One of the most common and underestimated sources of fundraising friction is manual reporting.
Spreadsheets passed between teams. Decks updated in parallel. Data pulled from multiple systems and reconciled hours before a meeting. Follow-up questions answered by combing through inbox threads and historical files.
Individually, these processes feel manageable. Collectively, they introduce small delays, inconsistencies, and moments of uncertainty. In a competitive fundraising environment, those moments accumulate.
Manual reporting does not replace performance as a decision driver. It shapes the pace and confidence with which decisions are made.
Manual Reporting Is More Than an Efficiency Problem
When reporting is manual, three things happen simultaneously:
Time is diverted from relationship-building to data assembly.
Inconsistencies creep in across materials.
Responsiveness becomes unpredictable.
When reporting relies heavily on manual workflows, the impact extends beyond internal productivity.
Time that could be spent deepening LP relationships is diverted toward assembling numbers. Data inconsistencies emerge as materials are updated in different places. Responsiveness becomes dependent on who has access to which file and how quickly it can be reconciled.
LPs rarely call this out directly. Instead, it surfaces through patterns. A follow-up question that takes longer than expected to answer. A metric that appears slightly different than in a prior presentation. A data room document that does not perfectly align with the most recent deck.
Each instance is small. None are fatal. But together, they create hesitation.
Over time, what began as a reporting workflow becomes a fundraising constraint.
LP Expectations Have Changed
Institutional LPs are more sophisticated than ever. Their internal processes are tighter. Their scrutiny is deeper. Their allocation committees are comparing managers side by side.
They expect:
Clean, consistent performance data
Clear segmentation of exposure and pipeline
Immediate access to historical reporting
Transparent audit trails
Fast turnaround on ad hoc requests
When firms rely on disconnected systems and spreadsheet workflows, meeting those expectations requires heroic effort. And heroics do not scale.
The Confidence Multiplier: Automation + Connected Data
Automation alone is not the solution. Nor is simply moving spreadsheets into a new interface.
The real shift happens when LP data, pipeline data, and performance data are connected in a unified system.
When reporting workflows are automated and built on a single source of truth:
Data populates consistently across decks, portals, and reports
Version control issues disappear
LP segmentation is dynamic rather than static
Response time to investor requests compresses significantly
Instead of reconciling discrepancies, conversations move directly to portfolio strategy and forward outlook. Instead of allocating time to assembling numbers, IR teams invest more time advancing relationships. Speed increases without compromising accuracy, and responsiveness becomes repeatable rather than reactive.
The result is not just operational efficiency. It is a measurable shift in how LPs experience the firm.
Faster LP Interactions Drive Fundraising Momentum
Fundraising is not just about capital availability. It is about momentum.
Momentum builds when:
LP follow-ups are answered quickly and cleanly
Materials reinforce rather than contradict prior communications
Data confidence reduces the need for repeated verification
Reference calls confirm operational discipline
Automation and connected systems accelerate each of these interactions.
In competitive processes, that acceleration matters. LPs notice who makes it easy to underwrite. They remember who is responsive under pressure. They favor managers who reduce internal friction.
The difference is subtle but compounding.
The Hidden Cost of “It Works for Now”
Many firms postpone modernization because manual reporting still functions adequately at their current scale. The spreadsheets balance. The decks go out on time. The raise eventually closes.
The more important question is whether those processes will hold under increased complexity.
As firms expand into continuation vehicles, co-invest structures, or multi-product platforms, reporting requirements multiply. Investor segmentation becomes more nuanced. Portfolio data becomes more layered. Regulatory scrutiny intensifies.
Workflows that felt manageable at Fund II often become strained by Fund IV. By the time the strain becomes visible externally, the internal opportunity cost has already accumulated in slower responses, extended diligence cycles, and heavier operational lift.
Raise Every Day Means Automate Before You Need To
High-performing IR teams do not wait for fundraising friction to force modernization.
They invest in:
Automated reporting workflows
Connected LP and pipeline data
Centralized CRM foundations
Real-time visibility into investor engagement
They understand that performance attracts capital, but operational clarity accelerates it.
When reporting is seamless and consistent, LP diligence moves more efficiently. When diligence moves efficiently, internal approvals progress with fewer delays. Over time, that compounding effect shapes not only how quickly capital closes, but how confidently LPs prioritize the relationship.
In today’s market, credibility is built in the details. And the systems behind those details often determine how much momentum a firm can sustain once performance has earned its place at the table.
Strong returns may open the door, but operational discipline determines how quickly LPs walk through it.
Fundraising conditions have shifted meaningfully over the past two years. Bain & Company’s Global Private Equity Report 2026 notes continued pressure on distributions and a record backlog of unrealized assets, contributing to slower capital recycling and tighter allocation pacing. At the same time, fundraising totals have moderated from peak years, and LPs are concentrating commitments among fewer managers.
In this environment, performance alone is rarely sufficient to drive fast re-ups. LPs are evaluating not only track record, but the operational infrastructure behind it. Institutional maturity has become a proxy for risk management.
Operational excellence, once considered back-office hygiene, now directly influences allocation velocity.
The Structural Shift in LP Evaluation
Private markets have grown more complex. Multi-strategy platforms, continuation vehicles, co-investment programs, private credit sleeves, and cross-border structures have expanded the operational surface area of firms. That complexity increases the importance of governance and reporting consistency.
ILPA’s Private Equity Principles and its updated reporting templates emphasize standardized reporting, transparency, and governance practices as industry best practices. These frameworks reflect rising LP expectations around auditability and comparability across managers.
At the same time, Coller Capital’s Global Private Capital Barometer has documented evolving LP sentiment, including greater caution around performance consistency and a heightened focus on risk mitigation in portfolio construction decisions. As performance dispersion narrows and public market comparisons intensify, differentiation increasingly depends on more than headline returns.
Taken together, these signals point to a deeper shift. LPs are underwriting operating models alongside investment theses.
They are assessing whether a firm’s systems, controls, and cross-functional alignment can support scale without introducing operational risk.
Where Operational Gaps Surface
Most firms do not view themselves as operationally fragile. The gaps often reveal themselves only under pressure, particularly during active fundraising or deep diligence.
They tend to surface in patterns rather than events. Numbers that require reconciliation across decks and portals. Investor segmentation that changes depending on who is exporting the data. LP requests that require manual aggregation from multiple systems. Reporting workflows that depend heavily on spreadsheet logic known to only a few individuals.
None of these issues, on their own, derail a fundraise. But together they introduce friction. And friction affects timing.
In a capital-constrained environment, timing matters. When LPs are consolidating commitments among core relationships, extended diligence cycles or slower responses can shift internal priority. Operational inconsistency does not always produce explicit concern; more often, it simply slows momentum.
What Operational Discipline Signals
When LPs encounter a firm with standardized, scalable systems, several inferences follow naturally.
First, the firm appears institutionally ready. Additional capital can be absorbed without destabilizing process.
Second, governance maturity is visible. Data is consistent across materials, traceable through workflows, and defensible in committee discussions.
For mid-market firms moving toward institutional scale, these signals are especially consequential. LPs want confidence that infrastructure is evolving at the same pace as strategy and AUM growth.
Operational clarity reduces cognitive load for allocators. That reduction in friction often translates into faster conviction.
Operational Infrastructure as a Fundraising Lever
Operational discipline is frequently framed as internal efficiency. In practice, it functions as an external confidence engine. But only when the underlying systems are connected.
Fragmented infrastructure creates invisible friction even when individual tools are performing well. A CRM that doesn’t communicate with the LP portal, a reporting workflow that requires manual reconciliation before each investor update, a data room that exists outside the firm’s core system of record: each of these represents a seam. LPs don’t see the tools. They see the outputs—response time, reporting consistency, narrative alignment across materials. When those outputs are uneven, the operational model behind them comes into question.
Integrated infrastructure changes what’s possible. When investor data lives in a single connected system, portfolio metrics reconcile automatically across decks, portals, and data rooms rather than requiring a reconciliation sprint before every LP touchpoint. Structured communication workflows that draw from shared data create consistent investor experiences across team members, fund vehicles, and time. Audit-friendly documentation emerges as a natural byproduct of how the firm operates rather than as a separate compliance exercise.
The integration itself is the signal. When an LP asks a question during diligence and the IR team, finance team, and deal team all produce the same answer from the same source, that alignment is evidence of an operating model that can absorb scale without introducing risk.
These systems do more than streamline internal work. They shift diligence conversations away from verification and toward forward strategy. When LPs spend less time validating numbers, they spend more time evaluating opportunity. When reporting is consistent across quarters and vehicles, reference checks reinforce credibility rather than surface discrepancies. When co-investment processes are organized and responsive because they’re embedded in the same system driving day-to-day IR operations, the experience compounds over time.
Integrated operational discipline, like performance, compounds.
Raise Every Day Means Operate Every Day
Firms that approach fundraising episodically often attempt to retrofit discipline when a new vehicle launches. High-performing firms embed readiness into daily operations. They align IR, finance, and deal teams around shared data foundations well before entering the market. They treat reporting consistency and governance not as compliance exercises, but as strategic assets.
In a market characterized by selective capital and heightened scrutiny, operational excellence is no longer a marginal advantage. It shapes allocation speed and commitment size.
The practical question for any firm is straightforward: if an LP initiated deep diligence tomorrow, would your systems accelerate confidence or introduce friction?
Altvia’s Fundraising Readiness Checklist outlines the structural components of scalable, compliant, investor-ready infrastructure and can help firms evaluate that question objectively.
In a tighter fundraising cycle, operational discipline is not merely about efficiency. It is about earning the credibility required to scale.
Private equity fundraising didn’t suddenly “change” in 2026. It tightened.
What’s different isn’t a brand-new set of rules. It’s the compounding effect of several forces that have been building for years: longer timelines, more competition for LP attention, and higher expectations for speed, clarity, and operational maturity.
In Altvia’s Fundraising in 2026: What High-Performing IR Teams Do Differently webinar, hosted by Ray Grant, Head of Strategic Initiatives at Altvia, and featuring Jeff Willems, COO of TritonLake, and Matt Curtolo, GP/LP Advisor at MC Advisory, LP and advisor perspectives converged on a single truth: performance is necessary, but it’s no longer sufficient.
Increasingly, LPs are selecting managers based on how the firm operates: how it communicates, how quickly it responds, how consistent its information is, and how well it manages relationships over time.
“It’s a progression. The environment remains challenging—and the bar is getting higher.” — Jeff Willems, COO, TritonLake
The macro signal: fundraising is down, but expectations are up
The webinar opened with a sobering data point: global PE fundraising declined in 2025 (S&P Global). Even without debating the exact “why,” the downstream effect is clear. In a tighter fundraising market, LPs have more leverage and more options.
That shows up in two ways.
First, LPs are concentrating capital with managers they already know. If an allocator has done the work, built conviction, and had a solid experience, there’s less incentive to “trade out” into unfamiliar names when the environment feels uncertain.
Second, LPs are looking harder at risk, not just investment risk, but organizational risk: how reliably a firm can execute, communicate, and run a disciplined fundraising process.
“Capital is concentrating with the perceived less risky, larger brand-name firms.” — Matt Curtolo, MC Advisory
For emerging and mid-market managers, this is where the game gets real. Differentiation isn’t just about strategy. It’s about building a machine that earns trust over time.
“Always be fundraising” is no longer a cliché—it’s a survival strategy
One of the clearest themes from the conversation: the fundraising process has evolved from a campaign into a continuous operating motion.
Five years ago, a manager could have a call, share materials, and move to a check within months. That environment—fast closes, compressed cycles—was an anomaly. Today, the cycle looks more like a relationship arc that can take years to mature.
Matt Curtolo put it succinctly:
“The best time to raise your next fund is the day after you close your last.”
This doesn’t mean spamming LPs indefinitely. It means you can’t disappear until you’re back in market.
LPs want to see lines, not dots: a clear progression of how a firm operates, performs, communicates, and follows through over time. That shows up in the fundamentals:
Touchpoints that demonstrate momentum and maturity—not noise
A practical tactic surfaced as well: invite prospective LPs into your ecosystem early. Annual meetings, updates, and thoughtful access points build familiarity before capital is on the table.
The diligence reality: LP attention spans are shorter, so relevance and responsiveness are everything
LPs are inundated.
“In my busiest year as an LP, I reviewed 500–600 opportunities. Last year, without even holding a formal LP seat, I still saw more than 600. That tells you everything: LPs are inundated. Attention spans are shorter. If you’re not building a long-term, compounding relationship, you’re just another cold outreach in a crowded inbox.” — Matt Curtolo
In 2026, LP diligence is faster and more comparative. Many allocators are evaluating multiple opportunities in parallel. That means the friction of getting information from a GP becomes part of the decision.
As Matt noted:
“If an LP has to chase you for information or follow up just to get clarity on your track record—and you don’t make time to respond—it erodes trust. In a competitive process, their focus will move elsewhere.”
Responsiveness, in other words, isn’t just a courtesy. It’s a signal.
But responsiveness only works when it’s paired with relevance. A scattershot approach, like sending your fund to every LP with a pulse, doesn’t build pipeline. It burns credibility.
The teams that stood out were the ones that:
Did the research upfront
Targeted LPs whose preferences matched the strategy
Articulated differentiation quickly and clearly
Followed up consistently (without being overbearing)
This is where many IR teams struggle—not because they don’t understand the principle, but because executing it at scale requires infrastructure.
The operating system: data, workflows, and institutional memory
A recurring point from the panel: relationships are human, but relationship management requires systems.
At a certain scale, “good memory” breaks. Notes get trapped in inboxes. LP preferences sit in spreadsheets that no one updates. Context gets lost. Follow-ups slip. The firm becomes inconsistent in the moments when it needs to be crisp.
This is exactly where high-performing teams build leverage: they turn relationship strategy into operational reality through centralized data and workflows.
One example shared: advisory teams use dashboards and tasks to manage follow-up cadences—including sensitivity to LP preferences. Some LPs welcome proactive follow-up. Others explicitly ask, “Send the materials, then leave us alone unless we reach out.” The workflow adapts.
As Jeff explains:
“At TritonLake, we make sure teams know when it’s appropriate to contact an LP and when it’s not. You don’t want to forget about an LP who’s in an advanced stage and hasn’t been contacted in several days; that needs to be addressed. We rely heavily on data and technology as enablers for that. You can’t replace relationships, of course, that’s crucial. Relationships are the driver. But you can use data and systems to ensure timely responses, avoid dropping the ball, and make sure you’re not reaching out with irrelevant information or hassling someone unnecessarily. That balance matters.”
Doing this well isn’t about more touchpoints. It’s about better ones.
AI is speeding diligence—but it won’t save messy operations
The panel’s AI discussion was refreshingly grounded.
AI is becoming embedded in fundraising and diligence, especially on the LP side: chat-style interfaces layered on data rooms, faster extraction of details, quicker synthesis of materials. On the GP side, AI can help query CRM data (“Who should I meet in Chicago next week?”), identify relevant prospects at events, and draft responses.
But the warning was clear: AI without clean data is noise, and automation without human judgment undermines trust.
As Jeff put it:
“AI should be an enhancement, not a replacement for human interaction.”
There’s also a compliance reality. Regulators are paying attention, meaning the near future is “AI-assisted, human-approved,” not fully autonomous LP communication.
Jeff explained further:
“You need to make sure your agentic AI takes compliance into account—SEC marketing rules, FINRA communication rules, all of it. The language has to be compliant, and communications must follow the regulations. At this stage, AI should be drafting the email and placing it in the advisory team’s inbox, where a human reviews and validates it before it’s sent. We’re still a long way from having AI speak directly to LPs. It should always enable the relationship—not replace it. The human element is key.”
Where Altvia fits: institutionalizing trust at scale
Put all of this together and the throughline becomes obvious: fundraising in 2026 rewards firms that can behave like institutions—without losing relationship quality.
That is exactly the problem Altvia is built to solve.
Altvia helps IR and fundraising teams:
Centralize relationship intelligence so LP preferences, touchpoints, and context don’t live in scattered notes or inboxes
Operationalize follow-up workflows that reflect real LP engagement styles (proactive vs. hands-off)
Improve responsiveness by making the right information easy to find, package, and deliver quickly
Create visibility into what’s working by tying activity to stage progression and outcomes—not just volume
Lay the foundation for responsible AI by ensuring data is structured, accurate, and usable
In a market where LPs can evaluate more opportunities faster, and where differentiation is increasingly operational, your IR operating system becomes part of your brand.
Fundraising isn’t just about what you say. It’s about whether your organization can consistently show up like the manager an LP can trust—today and two years from now.
If you want to win in 2026, don’t just refine your pitch.